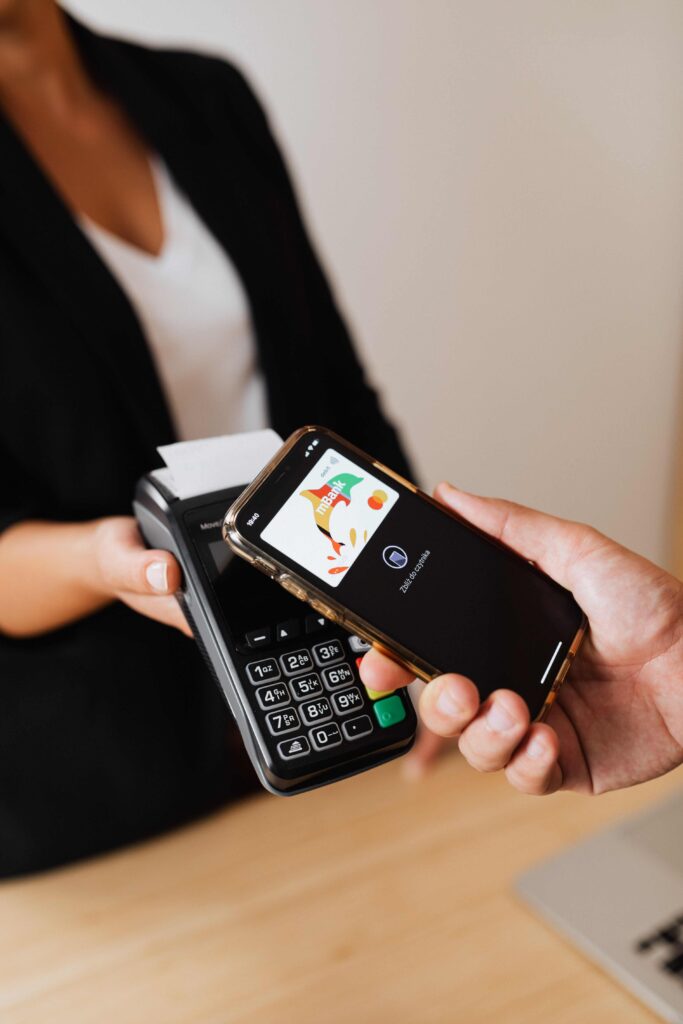
The Central Bank of Nigeria (CBN) has moved to stop any single bank or fintech from taking too large a share of the country’s payments market. The new market structure rules are aimed squarely at the big players in card issuing, POS terminals and digital banking, which includes names like OPay, Moniepoint and PalmPay.
If you use a fintech app to send money, pay bills or collect payments for your shop, here is what is going on and why it matters.
What the new cap says
Reports on the CBN’s market structure circular describe a balance rule between two sides of the payments business. An institution that handles more than 25% of consumer payments (the issuing side) is not allowed to hold more than 15% of merchant acquiring, which is the business of providing POS terminals and payment acceptance to sellers. The same limit applies the other way round.
The rule is also assessed at group level. Companies under common ownership or control are counted together, so a fintech cannot get around the limit by spreading its business across subsidiaries. The CBN has also said that institutions that break the rules can face supervisory sanctions under existing regulations.
When it takes effect
The reported compliance deadline is the end of December 2026, which is only a few weeks away. Affected companies are expected to file regular market share reports and show they meet the thresholds before that date. This follows earlier 2026 moves that required multi-product fintech groups to separate their licensed businesses with their own governance, capital and risk systems.
Why the CBN is doing this
Fintechs that began as merchant POS providers have grown into full digital banks, and a handful of them now process a large portion of everyday transactions. The CBN’s stated aim is healthier competition and a payments system that does not depend too heavily on a few companies. Critics point out that stricter rules can raise operating costs for fintechs, so the real effect will only show once the deadline passes.
What it means for everyday users
For most people, nothing changes overnight. Your wallet, transfers and cards keep working. Over time you may see:
- More choice of POS and payment providers, especially if you run a small business.
- Fintech apps adjusting fees or product bundles as they restructure.
- Smaller operators gaining room to compete.
If you want the wider picture of how the regulator treats fintechs, our guide on CBN fintech rules explained for everyday users covers the basics.
A sector with real career and study options
Rules like these are creating steady demand for compliance, risk, payments and data skills across banks and fintechs. If you are thinking of working in that space, it is worth checking open roles on the CMA9ja jobs board from time to time. And if you want to build the skills first, whether that is finance, law, data or software, the scholarships and study opportunities on CMA9ja Edu are a good place to look for funded routes.
Bottom line
The CBN is trying to stop payments from being dominated by a few firms, and the clock runs out at the end of 2026. Always confirm the final details on the CBN’s official website, because circulars can be clarified or amended before the deadline.
Join the discussion 0
No comments yet. Be the first to share your thoughts.